Wednesday, November 17, 2010
OK, Gold Correction Back On
Gold correction for November NOT aborted. To proceed per original fractal forecast. That forecast was for gold to have a weak spell up to around late November. Then a power climb to year end. It seems that silver wants to lead this upcoming charge, it has been much more extended on the upside lately. The gold/silver ratio is charging lower (see my previous posts) and silver, the higher beta of the twins, is so far being more muted on the downside in this pullback. The switch-over from silver under-performing gold to a sharp out-performance that began about a month and a half ago seems to be on course. This is the typical case for gold's mega moves - a severe catch-up climb for silver.


Saturday, November 6, 2010
Gold Correction Aborted
I wrote a piece back on October 18 about gaming the next gold correction anticipating a minor one for two or three weeks at least. Sure enough, the very next day, a correction started. It seemed to be advancing properly up until the "B" part of your standard abc corrective pattern that gold has been following up until now. But then it started behaving most improperly.

As the chart shows, as we started down from the "B", the market seems to have said,"OK, forget the rest of this correction. Let's get on with it." I suspected that maybe this pull back wasn't going to make much headway going into the sea of green building on the money flow chart. There is a big difference in buying pressure between now and July, when gold did its last "proper" correction. There was, however, much higher selling volume than buying volume as in a continuing correction. But the intensifying buying pressure seems to be snuffing out the effects of these profit takers.
This looks like an intensifying climb where the pull backs will be hard to figure.

As the chart shows, as we started down from the "B", the market seems to have said,"OK, forget the rest of this correction. Let's get on with it." I suspected that maybe this pull back wasn't going to make much headway going into the sea of green building on the money flow chart. There is a big difference in buying pressure between now and July, when gold did its last "proper" correction. There was, however, much higher selling volume than buying volume as in a continuing correction. But the intensifying buying pressure seems to be snuffing out the effects of these profit takers.
This looks like an intensifying climb where the pull backs will be hard to figure.
Monday, November 1, 2010
Is Silver Money ?
Gold is a metal that is garnering some attention these days as the "alternative currency" while the world seems bent on debasing all other currency. Historically, that has been gold's main utility, whether you show it off as a necklace or put it in a bank - it has been money down through the ages. But what about silver? We haven't made coins out of it for decades. It's commonly referred to as "the poor man's gold" and gold's ugly cousin and other derogatory phrases. And since the age of electronics has set in, 90% of it is used for such inglorious things as connections in our gizmos, which wind up at the bottom of our landfills.
It wasn't always like this for silver. The Greeks honored silver 2500 years ago by making it into coins, and, in fact for the next 2400 years, silver was the main means of exchange in daily commerce. Gold was used mainly just for big international trade or money actions between banks. As Milton Friedman once noted. "The major monetary metal in history is silver, not gold". It was 30 pieces of silver that betrayed Christ. If you look at the Bible or any old writings where the monetary metal pair is mentioned, it is typically "silver and gold" - not as we say today "gold and silver". It was today's ugly cousin who was the belle of the ball back then.
Is there any reason why silver, or gold, was viewed as money? Well, both metals are very rare. There are the so called "rare earth" elements, but they are actually quite abundant compared to gold and silver - just not as abundant as the base metals. So the monetary pair was given the status of the basis of exchange and the value ratio between them was set at around 15 - the gold/silver ratio (GSR). This ratio has become the subject of a lot of investor interest in our time as we try to value precious metals. There is geologic reason for the GSR being around 15 -17. Silver is 17 times more abundant in the earth's crust than gold on a parts per million basis.
The first few congressional coinage acts in America specifically set the gold/silver ratio at various numbers around 15. And even the Greeks set their ratios in the low teens. Governments have gone back and forth between silver and gold or both (bimetallism) as to what they set official money supply by. It turned out to be a complicated mess with both metals legal tender. When one metal price rose above the other, coins were melted down. But all money, especially the silver backed common exchange pieces, remained metal backed.
Then during the Civil War, Lincoln issued Greenbacks without metal backing to temporarily finance the war effort - our first paper money and our first adventure into fiat money. This instigated the "free silver" movement where the vast new silver finds in and around Nevada were argued as sound money expansion of the money supply. "16 to 1" became a hot political slogan of "the silver ticket". We endured this bimetallism approach to money with various coinage acts of Congress for most of our history. It was just from 1900 to 1971 that we were on an official gold standard. In the US of the late 1800s the rural farming population with a lot of debt and nagging deflation wanted bimetallism, a big debate of the day and the big issue in the 1896 presidential election.
The free silver rebels wanted both metals as money supply, the more ounces the better - a kind of early easy money policy, but all metal backed. It's been rumored that this debate was reflected in L. Frank Baum's "Wizard of Oz" originally published in 1900. The yellow brick road (gold) was originally traversed with Dorothy's silver slippers, later changed to ruby red. The "Oz" is thought to be a reference "ounce". But bimetallism, with all its complications, faded to a Congressionally mandated gold standard in 1900. Money supply was, however, expanded per the cries of the silver supporters with the issue of silver certificates backed by silver from 1878 to 1964 to circulate alongside the gold backed notes. But a movement away from the historical "silver as money" paradigm had begun. This really started us on a road past Dorothy's scarecrow of loose money that has strayed away from pure metal money to disruptive bouts with other types of money. Not long after the gold standard decree of 1900, we had currency mayhem. The Panic of 1907 resulted in the creation of the Fed in 1913 and, well, the rest is history :

This long-view chart shows what has happened to the gold/silver ratio since those days. It's basically been a story of the alternating periods in history where either paper was viewed as money or metals and hard assets in general were viewed as money. Wars, for whatever reasons, seem to bring the money view back to monetary metal and wind up putting the GSR back at 15. But disenchantment with paper bubbles sure seem to do the trick every time as the chart shows in the aftermath of 1929 and 1999. When we got away from making coins out of silver in the 1960s, we also ended the silver redemption of our bills that had "silver certificate" printed on them. Currency mayhem soon followed. It seemed like inflation was an unstoppable force ending the world as we knew it in 1980.
During the last portion of the great gold bull market of the 1970s, when metal again came to be viewed as money, there was a swift return to 16 to 1 on the chart. Silver has the tendency to lag the big moves in gold, then do a very swift catch-up move. This seems to be playing out now with our current gold market:

The red line is the gold/silver ratio, and it amazingly heads straight to the ancient 16 to 1 as the investor view is turned up to maximum "metal as money". If this happens yet again, it would put silver at $125 if gold were to go to $2000. That is a 400% gain on silver as compared to a 50% gain in gold. Fine tuning the gold/silver view even further, we see a sharp technical break in just the last month:

This indicates that the silver explosion over the latter portions of big moves in gold is starting.
But could we really drive silver to such outdated monetary levels? Consider that only 10% of the stuff goes to the investment market, and we are off any gold or silver standard now. Well, that was the case in 1980 and it didn't keep "16 to 1" from rearing its barbaric head. If you are wondering if we really equate silver with money nowadays, you need not look any further than an R-squared analysis between gold and silver prices of the last few years. Gold is clearly the money metal, and silver, despite having vastly different practical use fundamentals than gold, trades in near lockstep with gold with R-squared values around 0.96 (1.00 is a perfect correlation). Gold doesn't correlate this way with copper, sugar, or anything. Adrian Douglas has an excellent article at silverseek.com where he plots silver and gold prices from the last 6 years. He derives an equation just from the plots with the gold price as input and the silver price calculated solely from the gold price. He then plots a "synthetic" silver price (from the equation) and overlays this with the actual price chart for silver - the two graphs are nearly identical. He concludes that big money interests determine both the gold price and silver price. They view both as money nowadays.
Is silver money? History seems to say it was and is and will be the most basic money. We may be missing a passage in the Bible that reads, "Thou shalt be smitten with great calamity as thy path strays far from 16 to 1". In a world where all currencies are being debased, questioned, and abandoned, what if I told you there was a money that has been present and stable since the beginning of wealth, and that will give you 8 times the gain of gold as people flock to it? Silver may be just that.
It wasn't always like this for silver. The Greeks honored silver 2500 years ago by making it into coins, and, in fact for the next 2400 years, silver was the main means of exchange in daily commerce. Gold was used mainly just for big international trade or money actions between banks. As Milton Friedman once noted. "The major monetary metal in history is silver, not gold". It was 30 pieces of silver that betrayed Christ. If you look at the Bible or any old writings where the monetary metal pair is mentioned, it is typically "silver and gold" - not as we say today "gold and silver". It was today's ugly cousin who was the belle of the ball back then.
Is there any reason why silver, or gold, was viewed as money? Well, both metals are very rare. There are the so called "rare earth" elements, but they are actually quite abundant compared to gold and silver - just not as abundant as the base metals. So the monetary pair was given the status of the basis of exchange and the value ratio between them was set at around 15 - the gold/silver ratio (GSR). This ratio has become the subject of a lot of investor interest in our time as we try to value precious metals. There is geologic reason for the GSR being around 15 -17. Silver is 17 times more abundant in the earth's crust than gold on a parts per million basis.
The first few congressional coinage acts in America specifically set the gold/silver ratio at various numbers around 15. And even the Greeks set their ratios in the low teens. Governments have gone back and forth between silver and gold or both (bimetallism) as to what they set official money supply by. It turned out to be a complicated mess with both metals legal tender. When one metal price rose above the other, coins were melted down. But all money, especially the silver backed common exchange pieces, remained metal backed.
Then during the Civil War, Lincoln issued Greenbacks without metal backing to temporarily finance the war effort - our first paper money and our first adventure into fiat money. This instigated the "free silver" movement where the vast new silver finds in and around Nevada were argued as sound money expansion of the money supply. "16 to 1" became a hot political slogan of "the silver ticket". We endured this bimetallism approach to money with various coinage acts of Congress for most of our history. It was just from 1900 to 1971 that we were on an official gold standard. In the US of the late 1800s the rural farming population with a lot of debt and nagging deflation wanted bimetallism, a big debate of the day and the big issue in the 1896 presidential election.
The free silver rebels wanted both metals as money supply, the more ounces the better - a kind of early easy money policy, but all metal backed. It's been rumored that this debate was reflected in L. Frank Baum's "Wizard of Oz" originally published in 1900. The yellow brick road (gold) was originally traversed with Dorothy's silver slippers, later changed to ruby red. The "Oz" is thought to be a reference "ounce". But bimetallism, with all its complications, faded to a Congressionally mandated gold standard in 1900. Money supply was, however, expanded per the cries of the silver supporters with the issue of silver certificates backed by silver from 1878 to 1964 to circulate alongside the gold backed notes. But a movement away from the historical "silver as money" paradigm had begun. This really started us on a road past Dorothy's scarecrow of loose money that has strayed away from pure metal money to disruptive bouts with other types of money. Not long after the gold standard decree of 1900, we had currency mayhem. The Panic of 1907 resulted in the creation of the Fed in 1913 and, well, the rest is history :

This long-view chart shows what has happened to the gold/silver ratio since those days. It's basically been a story of the alternating periods in history where either paper was viewed as money or metals and hard assets in general were viewed as money. Wars, for whatever reasons, seem to bring the money view back to monetary metal and wind up putting the GSR back at 15. But disenchantment with paper bubbles sure seem to do the trick every time as the chart shows in the aftermath of 1929 and 1999. When we got away from making coins out of silver in the 1960s, we also ended the silver redemption of our bills that had "silver certificate" printed on them. Currency mayhem soon followed. It seemed like inflation was an unstoppable force ending the world as we knew it in 1980.
During the last portion of the great gold bull market of the 1970s, when metal again came to be viewed as money, there was a swift return to 16 to 1 on the chart. Silver has the tendency to lag the big moves in gold, then do a very swift catch-up move. This seems to be playing out now with our current gold market:

The red line is the gold/silver ratio, and it amazingly heads straight to the ancient 16 to 1 as the investor view is turned up to maximum "metal as money". If this happens yet again, it would put silver at $125 if gold were to go to $2000. That is a 400% gain on silver as compared to a 50% gain in gold. Fine tuning the gold/silver view even further, we see a sharp technical break in just the last month:

This indicates that the silver explosion over the latter portions of big moves in gold is starting.
But could we really drive silver to such outdated monetary levels? Consider that only 10% of the stuff goes to the investment market, and we are off any gold or silver standard now. Well, that was the case in 1980 and it didn't keep "16 to 1" from rearing its barbaric head. If you are wondering if we really equate silver with money nowadays, you need not look any further than an R-squared analysis between gold and silver prices of the last few years. Gold is clearly the money metal, and silver, despite having vastly different practical use fundamentals than gold, trades in near lockstep with gold with R-squared values around 0.96 (1.00 is a perfect correlation). Gold doesn't correlate this way with copper, sugar, or anything. Adrian Douglas has an excellent article at silverseek.com where he plots silver and gold prices from the last 6 years. He derives an equation just from the plots with the gold price as input and the silver price calculated solely from the gold price. He then plots a "synthetic" silver price (from the equation) and overlays this with the actual price chart for silver - the two graphs are nearly identical. He concludes that big money interests determine both the gold price and silver price. They view both as money nowadays.
Is silver money? History seems to say it was and is and will be the most basic money. We may be missing a passage in the Bible that reads, "Thou shalt be smitten with great calamity as thy path strays far from 16 to 1". In a world where all currencies are being debased, questioned, and abandoned, what if I told you there was a money that has been present and stable since the beginning of wealth, and that will give you 8 times the gain of gold as people flock to it? Silver may be just that.
Wednesday, October 20, 2010
China's Drag On The Market
I keep hearing and reading about how the market's outlook would be so much better without those darn Chinese. Yesterday you read that China sparked a sell off with their raise of interest rates. I've heard that the Chinese economy can't do well without the US consumer doing well, and we all know the US consumer of yester-year isn't coming back soon. As China goes, so goes the world, and the Shanghai has been in a sustained downtrend for over a year, being far in the red YTD. Well, take a peek at what's happening now.

William O'Neil, founder of IBD and a pretty sharp technical analyst, would look at this chart and have a cup and handle bottom reach off the screen and slap him. The handle is a little too long, but it's breaking, which would suggest that China's market is resuming a climb . China is moving to prevent bubbles. They are not stupid like our US leadership, so, yes, they are raising rates. And they are distancing themselves from not only US fiscal policy, but the US consumer as well, becoming a trading partner to the world.
Their stock market has spent most of this year below the critical 140 day ema (blue line) but has now regained the territory above it and turned its slope back to positive. China does indeed tend to be a harbinger for the rest of the world. Note that the bear decline for the Shanghai ended in October 2008. So the cup and handle breakage would predict a continued climb for global stocks. Other harbingers, like the QQQQ and the US transports are well above their April highs and point in the same direction for the broad market. China a drag on the market? Well, maybe not right now.

William O'Neil, founder of IBD and a pretty sharp technical analyst, would look at this chart and have a cup and handle bottom reach off the screen and slap him. The handle is a little too long, but it's breaking, which would suggest that China's market is resuming a climb . China is moving to prevent bubbles. They are not stupid like our US leadership, so, yes, they are raising rates. And they are distancing themselves from not only US fiscal policy, but the US consumer as well, becoming a trading partner to the world.
Their stock market has spent most of this year below the critical 140 day ema (blue line) but has now regained the territory above it and turned its slope back to positive. China does indeed tend to be a harbinger for the rest of the world. Note that the bear decline for the Shanghai ended in October 2008. So the cup and handle breakage would predict a continued climb for global stocks. Other harbingers, like the QQQQ and the US transports are well above their April highs and point in the same direction for the broad market. China a drag on the market? Well, maybe not right now.
Sunday, October 17, 2010
Gaming The Next Gold Correction
Gold has had a good run lately, and that begs the question, "When is the next correction and should I try to sell and buy back around it?" It's pretty easy to know when a correction is nearing. If you believe in the fractal voodoo, a one month correction is due to start around the end of October. It is of the type after a 64 day cycle that occurred in July this year, not the big four month type that started last December. So why not be clever and dance around it?
Well, if you had been clever enough to dance adroitly around the last two corrections, both the big one and the small one, this is how you would have done in all that tracks the price of gold (click on charts to enlarge):

It would have been worthwhile, putting you 7.7% and 5.5% ahead of a continuous hold. But when you try to apply this cleverness to individual gold stocks, this is the very typical result:

The cleverness backfires and instead of you gaming the corrections, Mister Market games you. And that's if you had timed both corrections to near perfection. In real life, that ain't likely. This doesn't happen with every stock, but it is the very typical case with the very small stocks (LODE, TRE, GBG, GRZ are some other examples). This is because the small miners have their stocks moved much more by their own individual property stories than by the short term fluctuations in the price of gold. It is a much bigger deal to them if a property is making good strides ahead than if gold goes $100 higher or lower. The big mature miners with a huge portfolio of producing properties see their stocks move much more in unison with the price of gold and silver. Trying to game corrections makes much more sense with them. But with the smaller miners, it becomes much more a roll of the dice.
As for a portfolio management strategy for gold corrections, it may make sense to raise cash with the gold and silver ETFs and large miners if you're attempting to trade as opposed to indiscriminate selling. When you are holding a quality junior miner, you are holding a development story that will jump the price of the stock at the most inconvenient of times for you as a trader.
Well, if you had been clever enough to dance adroitly around the last two corrections, both the big one and the small one, this is how you would have done in all that tracks the price of gold (click on charts to enlarge):

It would have been worthwhile, putting you 7.7% and 5.5% ahead of a continuous hold. But when you try to apply this cleverness to individual gold stocks, this is the very typical result:

The cleverness backfires and instead of you gaming the corrections, Mister Market games you. And that's if you had timed both corrections to near perfection. In real life, that ain't likely. This doesn't happen with every stock, but it is the very typical case with the very small stocks (LODE, TRE, GBG, GRZ are some other examples). This is because the small miners have their stocks moved much more by their own individual property stories than by the short term fluctuations in the price of gold. It is a much bigger deal to them if a property is making good strides ahead than if gold goes $100 higher or lower. The big mature miners with a huge portfolio of producing properties see their stocks move much more in unison with the price of gold and silver. Trying to game corrections makes much more sense with them. But with the smaller miners, it becomes much more a roll of the dice.
As for a portfolio management strategy for gold corrections, it may make sense to raise cash with the gold and silver ETFs and large miners if you're attempting to trade as opposed to indiscriminate selling. When you are holding a quality junior miner, you are holding a development story that will jump the price of the stock at the most inconvenient of times for you as a trader.
Monday, October 11, 2010
Maybe The Best Gold Stock You Never Heard Of
I've always held a deep respect for the thorough discounting efficiency of the stock market. In fact, my main analysis method depends heavily on it. So I tend to sneer at the "undiscovered gem" approach - "Oh, the market has discovered it, fool, and it knows more about it than you do" is my reaction. So, it is with a sense of uneasiness that I present to you an undiscovered gem.
Sante Fe Gold SFEG seems to be such a gem. It most certainly is undiscovered. Even amongst the small juniors, it is about the most unheard of, stealth gold stock priced above $1 I have ever run across. About the only people grabbing at it are the insiders, and they really like it. At an IH (insider held) factor of 35%, it is the 3rd most heavily insider held gold stock I have found (behind GORO and BVN) among the 60 or so I track that trade on US exchanges. And it's all officers who own, not funds or other companies, and some of the heavy handed buying has been just in the last year or so.
About the only hoopla one finds is some write-ups at investor village wherein they explain:

It has made much higher levels since mid '08, which is more than you can say for almost all the miners - a nice sustained uptrend that correlates well with the gold moves. It looks to be organizing for another sling shot move up with the current gold move:

Sante Fe Gold SFEG seems to be such a gem. It most certainly is undiscovered. Even amongst the small juniors, it is about the most unheard of, stealth gold stock priced above $1 I have ever run across. About the only people grabbing at it are the insiders, and they really like it. At an IH (insider held) factor of 35%, it is the 3rd most heavily insider held gold stock I have found (behind GORO and BVN) among the 60 or so I track that trade on US exchanges. And it's all officers who own, not funds or other companies, and some of the heavy handed buying has been just in the last year or so.
About the only hoopla one finds is some write-ups at investor village wherein they explain:
The average cash cost of production in the industry is about $580/oz for gold. I've seen figures of around $250 and $300-$400 projected for Sante Fe. It's been tabulated that M&A pricing metrics, as shown by the recent Andean Resources buyout, puts SFEG's current $1 stock at $36 by the same reserve oz valuation.And how did all this come to be? Essentially it has been borne out of an extremely conservative management style intent upon under-promising and over-delivering, that with little fanfare has been quietly and methodically acquiring additional properties at every opportunity, that not only hold great value already, they also hold additional superb upside discovery potential and at the same time sought to downplay expectations with initial extremely conservative projections based on $650 - $850 Gold prices along with conservative output projections and the prospect of better than expected grades, that might actually have a much better than expected impact, not only on the initial Gold and Silver output projections, but also on the bottom line due to what might be larger cost savings, along with a multiple increase in production, that has basically set the stage for an unexpectedly large increase in revenues, that a short time ago, did not even seem remotely possible even to us: And so now it appears as if the impending prospects of all this has certainly vindicated our judgment and decision to select SFEG as our preferred means of investing in Gold and Silver, with perhaps among the most upside leverage and potential for the coming year and early in this decade as we attempt explain further and offer some background as to how we came to this decision quite some time ago.And because we've had experience of this before, when we were able to identify extremely undervalued positions in both mining and other issues that were able to gain exponentially from similar, albeit much lower multiplier effects that still turned out to be very successful investments. With our track record of identifying ahead of time and capturing much of half a dozen up to 100 fold mega-winners this past decade We honestly have not seen a better, clearer or more easy to project so well ahead of time situation than Santa Fe Gold and re-iterate: Very few times in life are you ever likely to be faced with the prospect of being able to gain from a multiplier effect that you can see so clearly ahead of you especially any financial or investment multiplier because as you continue to evaluate Santa Fe's prospects
I've read a lot of complaining about the company's public relations efforts (or lack thereof). But they may be trying to fix this starting with an investor conference call this Friday. All of Sante Fe's operations are in the Southwest US and do not involve any geopolitical problems (unless Obama nationalizes the mining industry). Technically, the stock looks pretty interesting:In support of all this, 26 institutions considered Santa Fe to be a compelling enough investment proposition at $1.30 per share earlier this year and SFEG reached a high of $1.74. Therefore, since the fundamentals of the company are already substantially better today than they were then, with increasingly strong revenue growth forthcoming, Santa Fe would appear to be a rare and uncommonly undervalued and opportunistic anomaly in the current marketplace, in particular when compared with its peers.And with an additional 65 institutions or so that have either met with management personally, or by phone conferences and are now monitoring Santa Fe in expectation of an AMEX listing before too long, as Santa Fe continues to execute and potentially over-deliver, a real buying stampede in this issue could ensue, especially as important resistance numbers are taken out on the upside and most importantly, once new 52 week highs are reached and beyond new all time highs. And in addition to all of this, the company has already stockpiled more than a year's worth of production, presumably with all the intent to compress more than two years production into one and ultimately, ramp up in multiples of 400 tons per day sooner than anticipated, thus affording them a head start towards increasing to 1,000 tpd plus and very significant revenue growth.Sometimes it takes the marketplace time to factor in all of the information at hand and much of what is written above may not yet have been assimilated by all investors, but a few are beginning to get the memo and increasing numbers could begin to realize just how truly undervalued Santa Fe really is that at some point could create a rush on the stock and a bottleneck situation where demand for stock would overwhelm supply

It has made much higher levels since mid '08, which is more than you can say for almost all the miners - a nice sustained uptrend that correlates well with the gold moves. It looks to be organizing for another sling shot move up with the current gold move:

Tuesday, October 5, 2010
The Next Megatrend
I have found that investing is most easily done by identifying megatrends and working mostly within that area of the market with individual stock analysis. Studies have found that half of a stock's movement is a function of what its sector is doing. So if you're right about the major sector trends, you take positions in the best stocks and let them ride and trade only for very good reasons - "be right and sit tight" as the saying goes.
Gold is the megatrend right now. But all megatrends end. So what's after gold? If you're an investor who attempts to correctly switch horses when they die, you need to be thinking ahead and preparing to mount the next horse when the one you're charging ahead on is shot out from under you.
Before we consider what could possibly emerge as a megatrend after gold, let's first think about the shooting of the gold horse. I suppose the first thing that comes to mind when thinking about the end of something as hot as gold is your classic blowoff top followed by a catastrophic collapse that goes on for many years. This is what is thought of as coming after a parabolic rise. Isn't that what the Nasdaq of the 90s did and gold in 1980? Well, I would direct your attention to my previous article "The 64 Month Bull Market Fractal" to point out that the parabolas sometimes end that way, but can end with a jarring disconnect from the parabola followed by continued high range pricing and new highs - just without the nice smooth parabola. There is a current article over at Kitco by Chris Blasi suggesting that the macro economic conditions are so different now from 1980 that it almost dictates a different outcome in this gold bull market:
So what about a new megatrend to watch for? How about oil? When oil was passing $80 a barrel two years ago, it was about the only game in town and funds were loading the boat with it. All the oil bears were crying "speculative bubble", and when the financial collapse came in '08, it was just that - everything was a collapsing bubble then. Now oil is passing $80 a barrel again, and oil and the energy stocks are underperforming just about everything. They are the dog of the day now. You certainly can't blame the pricing on a frothy frenzy this time.
I think the price of oil may surprise and confound what I call "the barrel counters" - the energy planners who by and large are blind to the net energy crisis brewing in the world. They don't understand the profound decline in net usable energy coming from the industry. If you tabulate a real net usable energy curve, which used to be about one and the same with the raw barrel count, you get this disturbing picture (click to enlarge):

A sharp divergence between net energy and official barrel count began to emerge in 2005 - about the time the price of oil started going crazy. The Great Recession has perhaps camouflaged the real usable energy supply shortage since 2008. But now we have a recovering global economy matched against a steepening divergence between usable energy and barrel count - a double whammy that could bring three digit pricing back before we think. Crude alternatives are stepping in to fill the gap, but probably not fast enough. Oil has been a dog. But I have a hunch this dog will have his day.
Gold is the megatrend right now. But all megatrends end. So what's after gold? If you're an investor who attempts to correctly switch horses when they die, you need to be thinking ahead and preparing to mount the next horse when the one you're charging ahead on is shot out from under you.
Before we consider what could possibly emerge as a megatrend after gold, let's first think about the shooting of the gold horse. I suppose the first thing that comes to mind when thinking about the end of something as hot as gold is your classic blowoff top followed by a catastrophic collapse that goes on for many years. This is what is thought of as coming after a parabolic rise. Isn't that what the Nasdaq of the 90s did and gold in 1980? Well, I would direct your attention to my previous article "The 64 Month Bull Market Fractal" to point out that the parabolas sometimes end that way, but can end with a jarring disconnect from the parabola followed by continued high range pricing and new highs - just without the nice smooth parabola. There is a current article over at Kitco by Chris Blasi suggesting that the macro economic conditions are so different now from 1980 that it almost dictates a different outcome in this gold bull market:
Take a look at the US debt chart in this article and visibly compare 1980 to now - a vastly different condition as to its rapid healing prospects. So the shooting of our gold horse may actually be more of a moderate hobbling - but something to avoid nonetheless.Not a 70's gold bull replay.
True, gold's last bull run gave way to 20 years of price erosion, ratcheting down to the lowly exchange rate of $255 per ounce. Regardless, the US and global economic landscape of 2010 is vastly different than that of 1980. Today's exponential growth of sovereign debt is straining confidence in faith based currencies, particularly one which holds the mantle of world's reserve currency. This current debt differentiator, in conjunction with a myriad of other issues inhibiting US economic growth, is substantial enough to reasonably assure investors of a strikingly different course and conclusion to this gold bull.
So what about a new megatrend to watch for? How about oil? When oil was passing $80 a barrel two years ago, it was about the only game in town and funds were loading the boat with it. All the oil bears were crying "speculative bubble", and when the financial collapse came in '08, it was just that - everything was a collapsing bubble then. Now oil is passing $80 a barrel again, and oil and the energy stocks are underperforming just about everything. They are the dog of the day now. You certainly can't blame the pricing on a frothy frenzy this time.
I think the price of oil may surprise and confound what I call "the barrel counters" - the energy planners who by and large are blind to the net energy crisis brewing in the world. They don't understand the profound decline in net usable energy coming from the industry. If you tabulate a real net usable energy curve, which used to be about one and the same with the raw barrel count, you get this disturbing picture (click to enlarge):
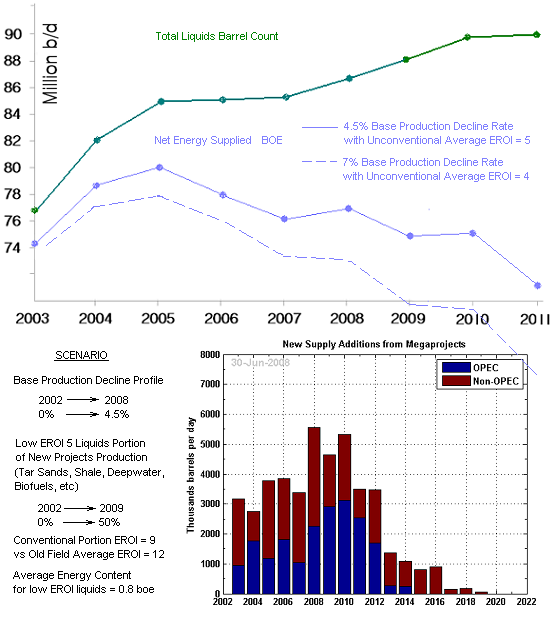
A sharp divergence between net energy and official barrel count began to emerge in 2005 - about the time the price of oil started going crazy. The Great Recession has perhaps camouflaged the real usable energy supply shortage since 2008. But now we have a recovering global economy matched against a steepening divergence between usable energy and barrel count - a double whammy that could bring three digit pricing back before we think. Crude alternatives are stepping in to fill the gap, but probably not fast enough. Oil has been a dog. But I have a hunch this dog will have his day.
Subscribe to:
Posts (Atom)